 The Independent Uganda: You get the Truth we Pay the Price

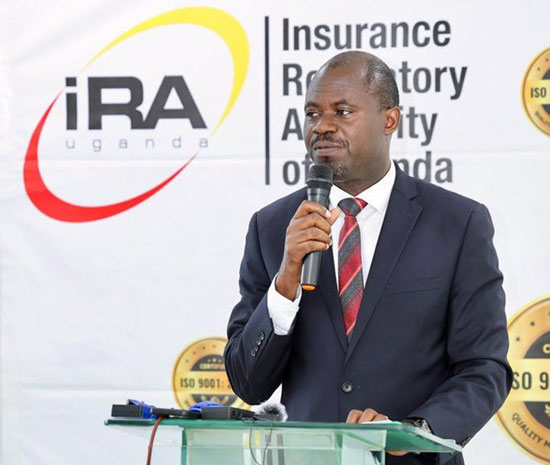
Life insurance accounted for almost half of premiums after growing more than 30 per cent, narrowing the long-standing gap with non-life business
Kampala, Uganda | THE INDEPENDENT | Uganda’s insurance industry has sustained gross written premiums above the Shs1tn mark for a second consecutive first half, suggesting the threshold is becoming a new base for the market rather than a one-off milestone.
Premiums reached Shs1.094tn in the six months to June 30, up 7.68 per cent from the same period a year earlier, according to Protazio Sande, acting chief executive of the Insurance Regulatory Authority of Uganda.
The latest figures point to a market that is expanding steadily while undergoing a significant shift in composition. Life insurance accounted for almost half of premiums after growing more than 30 per cent, narrowing the long-standing gap with non-life business.
The industry generated about Shs1tn in premiums over an entire year in 2020, compared with roughly Shs900bn in 2019. Reaching the same level in six months for a second successive year therefore offers a stronger indication of the market’s changing scale than the initial crossing alone.
The more important question for insurers now is whether this faster pace of premium growth can be sustained as Uganda’s economy expands and demand for long-term savings, health and risk protection increases.
Life insurance reshapes the market
Life insurance has emerged as the clearest source of momentum. Premiums in the segment rose more than 30 per cent to Shs524.14bn in the first half, giving life business almost 48 per cent of the overall market.
That growth has brought the two main segments of Uganda’s insurance industry closer together. Non-life insurance generated Shs552.9bn, leaving a difference of only 2.63 percentage points between the two.
For years, Uganda’s insurance market has been dominated by non-life products, including motor, property and other short-term risks. The growing weight of life insurance suggests a gradual broadening of the industry towards products with longer-term savings and protection features.
Sande described the growth in life insurance as positive for the wider financial system because it can create pools of long-term funds that can be invested in the economy.
“The growth in life is good news for the financial sector, for the country and for the wider economy,” he said.
The apparent decline in non-life premiums needs to be viewed in this context. The segment recorded a fall of about 7 per cent, but Sande attributed much of the movement to structural changes following the amalgamation of Jubilee Health and Jubilee Life.
Some business previously classified under non-life was transferred to the life segment, making the change in market shares partly a matter of reclassification rather than a deterioration in underlying insurance demand.
Claims remain a test of confidence
The growth in premiums is also being accompanied by a substantial increase in claims paid to policyholders.
Insurers paid Shs500.13bn in gross claims during the first six months, equivalent to about 46 per cent of premiums collected.
Life insurance accounted for Shs281bn of the claims, while non-life insurers paid Shs206bn. Health Maintenance Organisations accounted for Shs40.2bn and micro-insurance claims for about Shs710m.
The figures put claims settlement at the centre of the industry’s efforts to build consumer confidence. Uganda has long faced the challenge of persuading households and businesses that insurance provides meaningful protection rather than simply another cost.
Sande said the regulator was maintaining a zero-tolerance approach towards the non-payment of legitimate claims and would continue monitoring insurers where complaints or prolonged settlement periods point to weaknesses in liquidity, reserving or claims management.
“Effective and timely claim settlement remains fundamental for every insurance market,” he said.
For a market seeking to expand beyond its existing customer base, the ability to pay claims promptly may ultimately matter as much as the ability to sell new policies.
Banks become a bigger insurance gateway
Distribution is also changing. Bancassurance premiums rose 33.82 per cent to Shs183.9bn in the first half from Shs138.48bn a year earlier, reflecting the growing role of banks as a channel for selling insurance products.
Life insurance accounted for 79.14 per cent of bancassurance premiums, with non-life products making up the remainder. Banks earned about Shs24.72bn in commissions from the business.
The expansion gives insurers access to established banking relationships and allows banks to deepen their revenue streams beyond traditional lending and payments.
Insurance brokers remain another important distribution channel. They handled about Shs411bn in premiums during the period, compared with roughly Shs370bn previously.
Sande encouraged companies with large or complex risks to use professional brokers, particularly where specialised expertise is required to assess risks, negotiate cover and support claims.
Interestingly, micro-insurance remains small compared with the broader industry but is growing rapidly. Premiums in the segment rose 27.2 per cent to Shs2.67bn in the first half, highlighting the potential for specialised products aimed at customers who have traditionally remained outside the formal insurance market.
That market is particularly important in Uganda, where a large share of economic activity takes place outside the formal sector.
The challenge for insurers will be to develop products that are affordable and simple enough for mass-market customers while still commercially viable for providers.
A sustained expansion in this segment could eventually help move insurance from being concentrated among salaried workers and established businesses towards a broader household and small-business market.
Capital provides a buffer
The industry enters the next phase of growth with a relatively strong capital position. Total assets stood at about Shs3.77tn at the end of June, while the weighted average capital adequacy ratio was 271 per cent, well above the regulatory minimum of 200 per cent.
The buffer gives insurers room to absorb losses and meet obligations to policyholders, although the regulator is keeping a close watch on companies operating near the minimum threshold.
Sande said IRA would continue monitoring insurers whose capital positions could become vulnerable as risks evolve.
The relatively strong balance sheet is important as insurers prepare to take on larger risks associated with Uganda’s economic expansion.
Growth brings new risks
The outlook for the industry is closely linked to the country’s broader economic prospects.
Expected economic growth, controlled inflation, an expanding middle class and the anticipated start of commercial oil production could all increase demand for insurance.
Construction, engineering, transport and liability risks are likely to grow alongside investment in infrastructure and industrial activity, creating opportunities for insurers to move into larger and more sophisticated lines of business.
But economic expansion will also bring more complex risks. Geopolitical tensions and external economic shocks could affect investment returns, asset values and the cost of underwriting.
For insurers, the challenge is therefore shifting from simply expanding premiums to ensuring that growth is profitable and backed by adequate capital.
Sande urged companies to maintain disciplined underwriting, sound capital management and a stronger focus on policyholder value.
For Uganda, the significance of the latest figures may ultimately lie less in the Shs1tn milestone itself than in what happens next.
If the industry can consistently generate more than Shs1tn in premiums every six months, while expanding life insurance, improving claims settlement and reaching customers beyond the formal economy, insurance could become a more significant source of both household protection and long-term capital for the country’s development.
“Insurance is and should be your partner,” Sande said, urging households and businesses to incorporate insurance into their broader approach to managing financial risks.