 The Independent Uganda: You get the Truth we Pay the Price

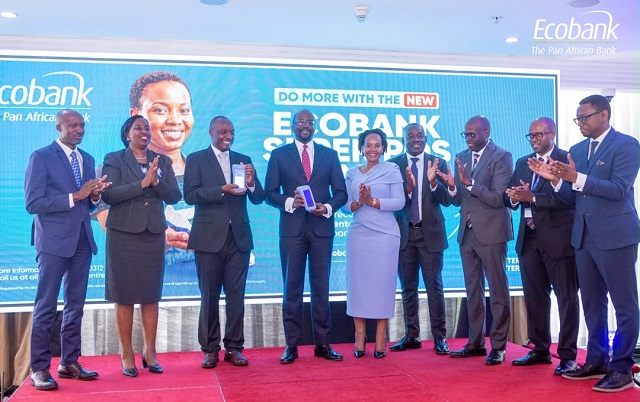
Kampala, Uganda | THE INDEPENDENT | Ecobank Uganda has launched a digital lending facility that allows eligible merchants to access up to Shs70 million in working capital based on their digital transaction history rather than physical collateral.
The Electronic Merchant Cash Advance (eMCA) is designed to provide short-term financing to businesses that collect payments through Ecobank’s Point-of-Sale (POS) terminals, web and Quick Response (QR) channels.
The bank said merchants become eligible after building at least three months of transaction history. An automated credit system then determines the facility limit, which can be up to 50% of the merchant’s average monthly digital collections.
The facility is disbursed digitally after the merchant accepts the offer and confirms the transaction using a one-time password. Repayment is made in a single settlement within 30 days and is automatically deducted from the merchant’s collection flows.
Ecobank said the facility does not require collateral, paperwork or a branch visit.
The lending model comes as small and medium enterprises continue to face challenges accessing conventional credit, particularly where loans require assets such as land titles as security.
For businesses with regular sales, the timing of payments can also create a short-term financing gap, leaving them unable to restock, pay suppliers or respond to increased demand despite having an active customer base.
Speaking at the launch, Grace Muliisa, Managing Director of Ecobank Uganda, said the facility was intended to support the country’s economic growth ambitions by making working capital more accessible to smaller businesses.
“Uganda has set itself the ambition of growing its economy tenfold by 2040, and no economy grows tenfold on the back of large corporates alone. It grows when the supermarket in Kabalagala, the hotel in Jinja and the clinic in Mbarara can all finance their next order without pledging a land title. eMCA is our contribution to that national agenda. It takes the everyday commerce Ugandan businesses already generate and turns it into credit, at speed and at scale. When capital moves faster through the real economy, inventory turns faster, suppliers are paid on time, jobs are created and tax revenue grows. That is how a banking sector participates in national transformation rather than merely observing it.”
The facility relies on transaction data generated through digital payments. As merchants receive more payments through Ecobank’s channels, the bank can build a record of their sales and use it in determining their access to credit.
Emmanuel Kikoni, Head of Cash Management at Ecobank Uganda, said the approach changes the information traditionally used in assessing small- business borrowers.
“For decades, the question a Ugandan business heard from its bank was what do you own. eMCA replaces that with a better question: what do you sell. We already see the pulse of a merchant’s business in their collections, so the credit decision can be made by a scoring engine in minutes rather than by a committee in weeks, and repayment can be collected automatically from the same settlement flows that earned the limit in the first place. That is a genuinely new operating model for lending in this market. It has been tested end to end with Ugandan merchants, and it runs on the same digital collections and cash management rails our clients already use every day. Innovation, for us, is not a pilot in a laboratory. It is a product a merchant can draw down before lunchtime.”
The initial rollout will target businesses in retail, hospitality, food and beverage, fuel, health and leisure, which the bank identifies as sectors with frequent transactions and relatively consistent daily cash flows.
The facility has an access fee of 3%, according to Evans Katwebaze, Head of SME and Value Chain at Ecobank Uganda.
“At our SME Breakfast, business owners told us plainly that the difference between growing and standing still is often a few days and a few million shillings. A restaurant that cannot restock on a Friday loses the weekend. A hotel that cannot pay a supplier loses the booking. eMCA is built for that moment. It is unsecured, it is priced transparently at a three percent access fee, it is available up to fifty percent of a merchant's average monthly collections, and it is repaid quietly out of settlements so the owner can concentrate on trading. Just as importantly, it rewards formalisation. The more a business channels its sales through formal digital collections, the more visible its performance becomes and the larger the facility it can command. That is a value proposition that grows with the customer rather than gating them at the door.”
The model therefore links a merchant’s payment activity to its potential access to short-term financing.
However, the facility’s reach will initially depend on businesses already using Ecobank’s digital collection channels. The bank said it plans to progressively extend the service to newly onboarded businesses as it expands its acquiring network.
The launch comes against the backdrop of Uganda's Tenfold Growth Strategy, which seeks to expand the economy from about US$50 billion to US$500 billion by 2040. The strategy places a significant role on private- sector growth, including small and medium enterprises.
Ecobank said merchants interested in the facility can engage their relationship managers or visit an Ecobank Uganda branch to begin collecting payments through the bank’s digital channels.
The eMCA adds lending to the bank’s existing digital payments, collections and cash-management services, effectively using transaction flows as the basis for determining short-term working capital.