 The Independent Uganda: You get the Truth we Pay the Price

Kampala, Uganda | JULIUS BUSINGE | Uganda’s ambition to expand its economy tenfold to $500 billion by 2040 will depend partly on the ability of businesses to invest productively, manage financial risks and convert the country’s natural resources into higher-value products. That puts chief financial officers (CFOs) at the centre of the country’s economic transformation agenda.
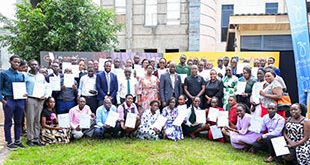
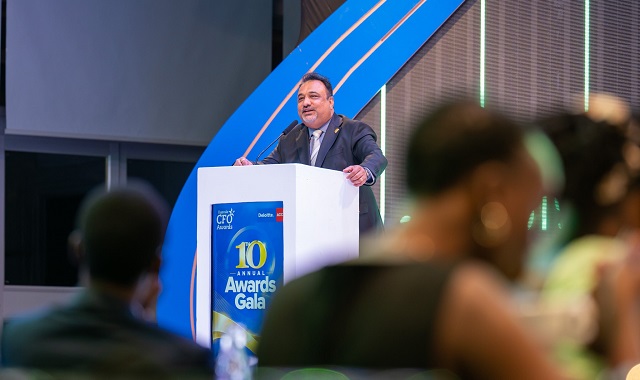
The message emerged at the 10th Uganda CFO Awards, held at Kampala Serena Hotel recently, where business leaders and policymakers challenged finance professionals to move beyond traditional accounting and become more involved in investment decisions, corporate strategy and long-term value creation.
The awards, organised by the Association of Chartered Certified Accountants (ACCA) Uganda and Deloitte Uganda, came as government implements the Fourth National Development Plan (NDP IV), which seeks to accelerate industrialisation, increase productivity and expand private- sector investment as part of the tenfold growth strategy.
For Uganda, the policy challenge is not simply to attract investment into agriculture, manufacturing, mining, oil and gas or tourism. Businesses must also allocate capital efficiently, manage operating costs, meet regulatory obligations and demonstrate that investments can generate sustainable returns.
Sanjay Tanna, Minister of Trade, Industry and Cooperatives and chief guest at the awards, urged finance leaders to help businesses identify growth opportunities while maintaining financial discipline.
He pointed to sectors with potential to drive Uganda’s economic expansion, including agro- processing, coffee, tea, dairy, shea butter, cocoa products, mining, copper, gold, oil and gas, and tourism.
These sectors offer opportunities to move beyond exporting raw commodities towards processing, manufacturing and other activities that retain more value within the country. But doing so requires businesses to make sound investment decisions, assess commercial risks and ensure that expansion plans are supported by credible financial strategies.
The CFO, therefore, has a role that extends beyond preparing accounts and reporting past performance. Finance leaders must help management determine which projects deserve investment, how they should be financed and whether expected returns justify the risks.
From numbers to strategy
Josephine Okui Ossiya, chief executive officer of the Capital Markets Authority (CMA), said the modern CFO must be an active participant in shaping organisational decisions rather than simply explaining financial results after decisions have been made.
“The finance function is sometimes called to provide the answer after everyone else has made the decision. In reality, its greatest value is often in helping shape the question before the decision is made,” she said.
Her remarks point to a broader governance issue for Ugandan businesses: financial information is useful not only for statutory reporting but also for determining whether corporate strategies are realistic, affordable and sustainable.
For companies investing in factories, processing facilities, technology or new markets, financial leaders must test management assumptions against available resources, projected revenues and potential risks. They must also explain difficult financial results honestly to boards, investors, lenders and regulators.
Ossiya identified trustworthy financial information, financial discipline, responsible technology adoption, sustainability and the development of young professionals as critical responsibilities for CFOs.
She also linked sound financial governance to the development of Uganda’s capital markets and access to long-term financing.
This has implications for businesses seeking to raise capital to expand production. Investors and lenders need reliable information to assess a company’s financial position, repayment capacity and growth prospects. Weak disclosure and poor financial controls can undermine confidence, potentially making financing more difficult or expensive.
Well-governed companies, on the other hand, are better positioned to demonstrate their credibility and attract investment for productive activities.
The issue is particularly relevant to smaller businesses seeking to move into formal manufacturing and agro-processing. Their growth depends not only on access to finance but also on the quality of financial records, internal controls and management systems needed to secure and use that funding effectively.
The value-addition test
Government’s development strategy places considerable emphasis on increasing production and value addition across agriculture, minerals, oil and gas, tourism, information and communications technology, and financial services.
Under NDP IV, agro-industrialisation is intended to increase agricultural productivity, expand processing capacity, create jobs and raise exports of agricultural commodities and processed products. The plan also identifies increased agricultural financing as an important objective.
For CFOs, the challenge is to make these ambitions commercially viable.
A coffee processor, for example, must evaluate the cost of sourcing beans, installing processing equipment, maintaining quality standards, accessing export markets and managing fluctuations in prices and foreign exchange. A dairy business must weigh investment in collection systems, refrigeration, processing and distribution against expected demand and operating costs.
Similar calculations apply to mineral processing and the development of supply chains linked to Uganda’s emerging oil and gas industry.
The availability of raw materials does not automatically guarantee profitable processing businesses. Companies must establish whether infrastructure, energy, labour, financing and market conditions support competitive production.
Finance chiefs can help identify these constraints before capital is committed, while monitoring whether public and private investments deliver the intended economic benefits.
At the national level, this raises a policy question: how effectively are businesses translating Uganda’s production potential into competitive industries that create jobs, increase exports and broaden the tax base?
The contribution of finance leaders will partly depend on whether their organisations prioritise productive investment and sustainable expansion over short-term financial gains.
Technology and accountability
The awards also highlighted the growing influence of technology, particularly artificial intelligence, on financial management.
Tanna encouraged organisations to embrace AI, arguing that businesses that adopt emerging technologies could be better positioned for the coming decade. He cautioned, however, that technological change must not weaken professional ethics and accountability.
“Numbers may change. Technology will certainly change. The role of the CFO will continue to change. But trust will always remain at the centre of leadership,” he said.
For finance departments, digital tools can improve the speed of reporting, data analysis, forecasting and risk identification. But technology cannot replace professional judgement, independent oversight or responsibility for the accuracy of financial information.
This is important as businesses increasingly rely on automated systems to support decisions involving investment, lending, procurement and financial controls. CFOs must ensure that efficiency gains are matched by appropriate safeguards, data quality and accountability.
Ossiya also challenged finance leaders to invest in developing the next generation of professionals, pointing to mentorship as part of their wider leadership responsibility.
A decade of changing expectations
The awards’ tenth edition reflected the expanding expectations placed on the profession.
According to ACCA and Deloitte, the 2026 competition attracted 407 nominations, with 37 CFOs qualifying from 53 assessed candidates. Twenty-one of the qualifying finance chiefs were participating for the first time.
Charlotte Kukunda, ACCA Uganda country manager, said the awards had evolved from four categories to nine, reflecting changes in the responsibilities of finance professionals.
Yusta Kasenge, a partner at Deloitte East Africa and CFO programme leader for Tanzania, said the CFO position should not be viewed as the final destination of a professional career. Instead, it can provide a route into broader executive leadership.
The experience of previous award winners illustrates this progression, with some moving into managing director and other senior executive positions.
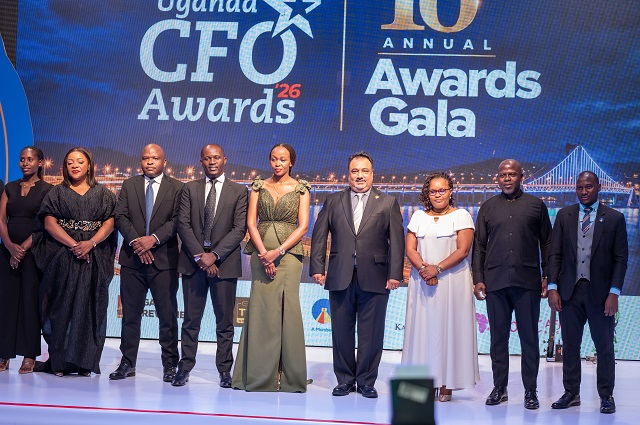
The 2026 overall award went to Fredrick Kakooza, chief finance officer at Quality Chemical Industries Limited, who also won the Leadership Award. Josephine Njoroge, finance director at Uganda Breweries Limited, was named first runner-up and received the Strategy Execution Award.
Other winners included Caroline Akello of Acclaim Africa Limited, who received the Young CFO Award; Ronald Makata of Stanbic Bank Uganda, who won the Sustainability Award; and Susan Taffumba Isubikalu of Uganda Electricity Generation Company Limited, who won the Public Sector Award.