 The Independent Uganda: You get the Truth we Pay the Price

The decision highlights a commercial trade-off facing banks as they expand digital services
Kampala, Uganda | JULIUS BUSINGE | NCBA Bank Uganda has waived transaction fees on selected digital banking services until the end of the year, seeking to ease customers’ financial burden while encouraging greater use of its digital platforms.
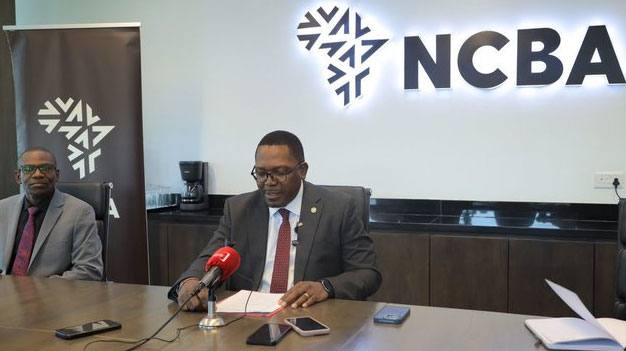
The campaign, launched on October 13 at the bank’s headquarters in Kampala, offers zero transaction fees on eligible services accessed through the NCBA NOW mobile application, web banking and USSD channel.
The initiative comes as households and businesses contend with rising operating costs, including fuel prices, which have increased pressure on disposable incomes and business cash flows.
Under the campaign, customers will not pay transaction fees on selected services, including utility bill payments, bank-to-wallet transfers, electronic funds transfers (EFT), Real-Time Gross Settlement (RTGS), international transfers and National Social Security Fund (NSSF) payments. The offer runs until December 31, 2026, subject to applicable terms and conditions.
Affordable banking
The Bank’s Managing Director Mark Muyobo said the initiative was intended to make banking more affordable and accessible, allowing customers to pursue their ambitions without unnecessary financial barriers.
“Our customers are going through tough times. This is an opportunity for us to support them through the challenges at hand, particularly the cost of doing business and fuel prices,” Muyobo said at the launch.
He said the bank was prepared to forgo transaction-fee income to provide relief to customers during the remainder of the year.
“There is an impact on revenue. It is not about the financial gain, but something we are willing to forfeit on behalf of the customer so that we move with them through this tough period,” he said.
The decision highlights a commercial trade-off facing banks as they expand digital services: whether to retain fees on transactions or sacrifice some income to encourage customers to transact more frequently through lower-cost channels.
For NCBA, the campaign combines short-term customer relief with an incentive to increase activity on its digital platforms. It targets existing customers, including those whose accounts have become inactive, as well as prospective customers seeking more affordable banking services.
Customers can access the services through the NCBA NOW application, online banking or the *212# USSD channel.
Muyobo said the bank was also encouraged by developments in the financial services market that were giving customers more options at lower costs. He noted that the cost of providing some financial services had been declining, creating opportunities to deliver greater value to customers.
The longer-term commercial benefit will depend partly on whether the fee waiver translates into sustained digital adoption, more active accounts and stronger customer relationships after the campaign ends.
Digital banking enables customers to make payments and transfer money without visiting branches, potentially reducing the time and costs associated with routine transactions. For banks, greater digital usage can also help shift transaction volumes away from physical service points, although digital platforms still require investment in technology, security and customer support.
Existing campaigns
NCBA’s latest campaign complements its existing “Ku NCBA Kiggwa Ku Bwererere” initiative, which targets small and medium-sized enterprises (SMEs). Unlike the new campaign, which focuses on individual customers, the SME initiative seeks to reduce business financing and banking costs.
Qualifying businesses can access zero transaction fees and zero arrangement fees on selected facilities, including business loans, invoice discounting, local purchase order (LPO) financing and asset financing, subject to the applicable terms.
The two initiatives reflect the bank’s effort to address costs affecting both households and businesses, although their commercial implications differ. Individuals are being encouraged to use digital banking more actively, while businesses are being offered relief on selected banking transactions and financing-related charges.
For SMEs, which often operate with limited cash reserves and face pressure to manage working capital, lower transaction and financing costs can free up resources for daily operations. However, the extent of the benefit will depend on the facilities used, eligibility requirements and the duration of the offers.
Muyobo did not disclose the expected revenue impact of the new campaign or the volume of transactions it hopes to attract before the December deadline.
The campaign nevertheless places affordability at the centre of the bank’s digital strategy at a time when customers are increasingly weighing the cost of financial services alongside convenience.
Whether the initiative produces lasting changes in customer behaviour will become clearer after the promotional period, when transaction fees on eligible services may revert to the bank’s applicable tariff.